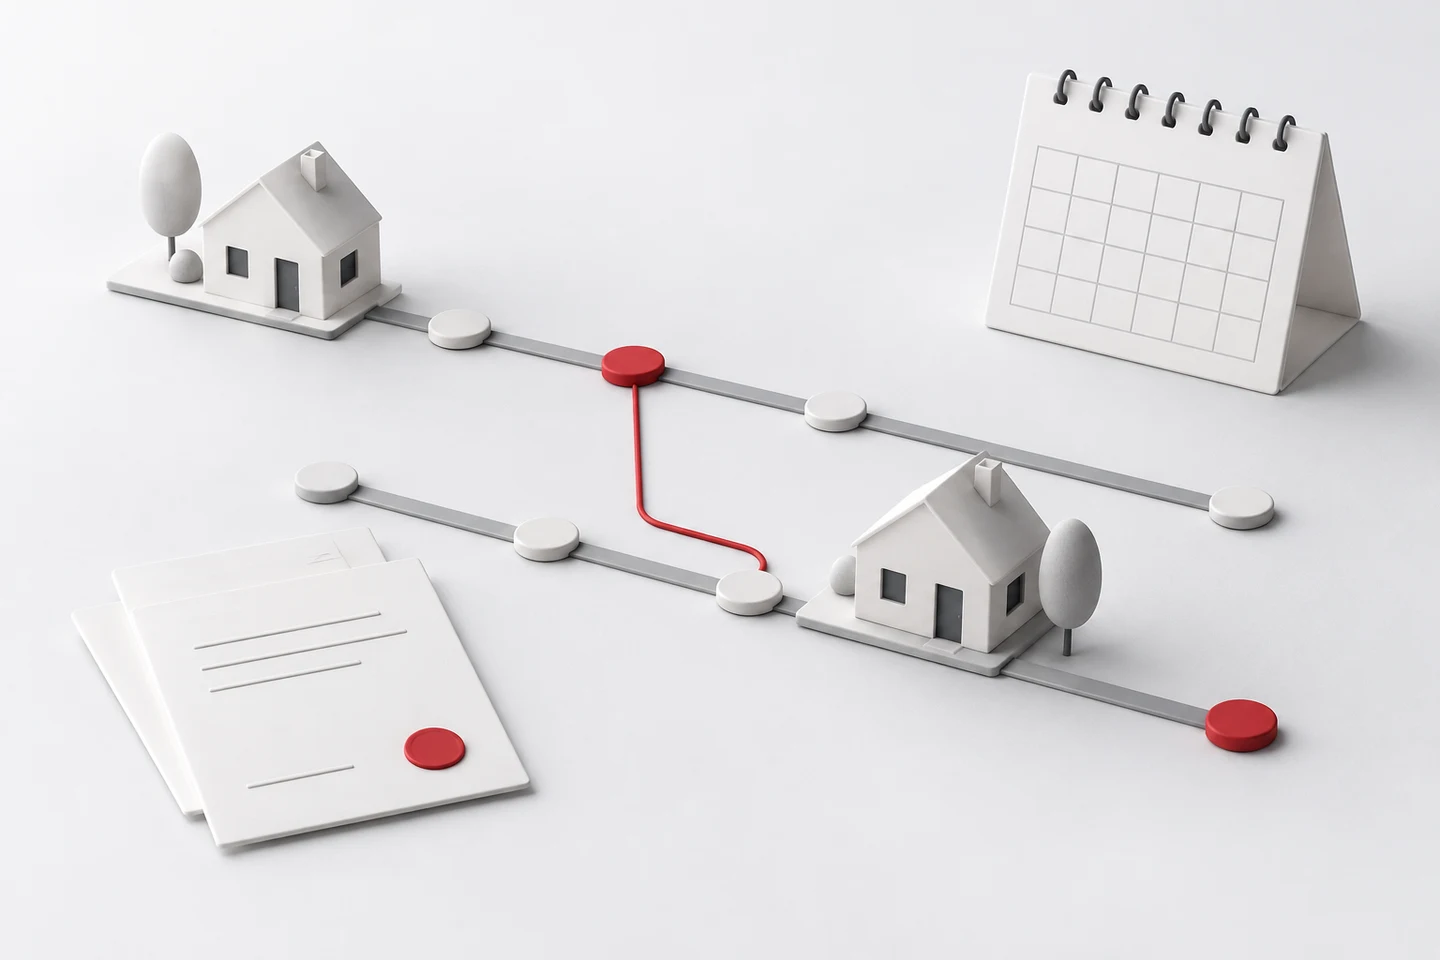
A purchase that depends on selling another home has two calendars. One tracks the sale of the current property; the other tracks the new purchase and its mortgage. The useful question is not simply, “When do we hope to move?” It is, “Which event must happen before the next deadline, and what does the contract require if it does not?”
Put both transactions on one dated schedule as soon as the new offer is accepted. Mark deadlines for notices as carefully as closing dates. An expected closing date is a planning assumption until the sale closes and the necessary funds are available.
Know which condition is in the contract
A home-sale contingency gives a buyer time to sell a current home before closing on the new one. A home-close contingency addresses a later stage: the buyer already has a contract for the current home but needs that sale to close before buying the next property. The distinction matters because an accepted offer on the old home is not the same event as a completed sale. The National Association of Realtors’ consumer guide identifies these as separate contingencies and stresses that their timelines belong in the signed agreement.
A seller may also negotiate a kick-out clause while accepting a contingent offer. If another acceptable offer arrives, the clause may give the first buyer a specified opportunity to proceed without the sale or close contingency. The notice method, response period and proof required are matters to read in the actual clause; “we can probably sell in time” may not satisfy it. A right to continue showing the property and a right to end the first contract are related, but their exact terms should not be assumed from a label.
Ask the agent to point to the precise event that satisfies each condition. Does “sell” mean listing the old home, signing a sale contract, removing that contract’s conditions, or closing? If the buyer of the old home withdraws, does the purchase protection still apply? The signed contract and applicable local forms control those answers.
Build one timeline from offer acceptance to closing
The schedule below is an illustration, not a standard set of contract periods. Replace every day with the dates and notice rules in the signed documents. Work backward from the proposed new-home closing, leaving room for the old sale, loan work and document review.
- Day 0: New-home offer accepted. Record the effective date used by the contract, the sale or close contingency deadline, the proposed closing date and each party responsible for sending notices. Check whether a deadline is measured in calendar days, business days or by a stated date and time. Put the financing, inspection and other purchase deadlines on the same schedule; a sale contingency does not automatically extend them.
- Early period: Current home listed or its status confirmed. If the old home is not under contract, record any listing deadline and what evidence the new-home seller must receive. If it is already under contract, obtain its inspection, financing and closing dates. An old-home buyer’s unresolved condition can affect the onward purchase even when the sale contract has been signed.
- Old-home contract reached. Note the date an offer is accepted, the agreed closing date and the conditions the old-home buyer still has to meet. Tell the new-home agent and lender what changed, using the documents they request. Check whether this milestone satisfies the purchase contract’s home-sale condition or merely starts the next stage of a home-close condition.
- New mortgage deadlines met. Track the purchase contract’s financing date separately from the lender’s document requests, appraisal, underwriting and funding steps. Ask the lender which evidence of the old sale it needs and when. A loan decision based on expected proceeds may still leave a practical gap if those proceeds are unavailable at funding.
- Closing Disclosure received and reviewed. For mortgages covered by the requirement, the lender must provide the Closing Disclosure at least three business days before mortgage closing. Compare the final loan terms, projected payments and closing costs with the Loan Estimate. Ask the lender promptly about errors or unexpected changes. Put the disclosure receipt and review on the calendar; do not treat the closing appointment as the first chance to examine the figures.
- Old-home sale closes, then new-home purchase closes. Confirm when the old sale is complete, when its proceeds will be available and when the new lender and settlement agent need funds and documents. At the purchase closing, the settlement agent coordinates contractual obligations, funds and documents; the seller signs the deed transferring ownership. The Consumer Financial Protection Bureau’s closing guide explains those steps. Two appointments on the same day do not, by themselves, prove that the first transaction can fund the second in time.
When one date changes, check its dependants
An accepted offer on the old home can satisfy one condition while leaving its buyer’s inspection or financing unresolved. A later old-home closing can affect the new lender’s funding date even if the purchase contract’s financing deadline has passed. Check each affected date separately: the contingency deadline, any kick-out response, loan approval, disclosure review, both closings and possession. Ask which party needs written notice or an extension. Record the answer and the date it was given.
Handle a slip before it becomes a missed deadline
Suppose the old home is under contract, but its buyer requests a later closing. First, identify what has changed: the date alone, an unresolved inspection or loan condition, or the likelihood that the sale will complete. Then read the new purchase agreement for its home-close deadline, financing deadline and closing date. They may be different dates, and moving one does not necessarily move the others.
Ask the old-home closing professional for the best supported date, then ask the new-home lender and settlement agent whether that date still allows the purchase to fund and close. Give the new-home seller an accurate update through the agent. If an extension is needed, have the appropriate professionals put it in writing and obtain the required signatures before relying on it. Keep a record of when notices were sent and received.
The same discipline applies if a kick-out notice arrives. Read the clause immediately with the agent and, where appropriate, a local real estate attorney. Establish the response deadline and the specific act required to keep the contract. Do not assume that obtaining an offer on the old home removes a contingency that calls for its closing, or that a verbal assurance changes a written deadline.
Questions to ask on both sides of the deal
If you are buying with a sale or close contingency, ask your agent: What exact event satisfies it? Which documents prove that event? How must we give notice, and to whom? Can the seller continue to show the property? If a kick-out notice arrives, what must we do and by when? Which inspection, financing and closing dates would remain in force if the old sale moved?
Ask your lender: Does approval depend on the old home’s sale proceeds or on paying off its mortgage? What proof of the sale will underwriting require? When must the proceeds be available for funding? If the old sale closes later or nets less than expected, which loan terms need another review? When should the Closing Disclosure arrive, and whom should you contact about a discrepancy?
If you are selling to a buyer with a contingency, ask your agent: Is the buyer’s home merely listed, under contract or close to closing? What milestone and deadline has the buyer actually promised? What information may you request to confirm progress? Can you keep showing your property, and what must happen before you can act on another offer? Ask your own lender or closing professional which obligations depend on your sale date if you are also buying.